1031 Exchange

4 Documents to Provide Your CPA for Reporting a 1031 Exchange

1031 Exchange Tax Documents

Many taxpayers conducting 1031 exchanges want to know what information they need to provide to their CPA or tax accountant when reporting a 1031 exchange transaction. In this article, we will outline four essential documents to provide your CPA when reporting your 1031 exchange.

Information to Provide Your CPA

Every 1031 exchange situation is different, so you should talk to your CPA or tax accountant about your specific situation to see what documents they will need. That being said, typically they will want to see the following documents in order to complete the IRS Form 8824:

  1. Relinquished Property Closing Statement and may want to review the signed 1031 Exchange Agreement and Relinquished Property Assignment Agreement

  2. Replacement Property Identification Form (if any)

  3. Replacement Property Closing Statement and may want to review the Replacement Property Assignment Agreement

  4. Close-out Letter from the Qualified Intermediary

Your qualified intermediary can provide scanned PDF copies of any documents related to your 1031 exchange that your CPA or tax accountant may need.

Contact a Qualified Intermediary

If you need any assistance with your 1031 exchange, look no further than CPEC1031, LLC. Our qualified intermediaries have been facilitating exchanges of all shapes and sizes for more than two decades. We have the knowledge and experience needed to ensure your exchange is a success. Reach out to us today to learn more about the full extent of our services and see how we can help with your next 1031 exchange of real estate.

  • Start Your 1031 Exchange: If you have questions about 1031 exchanges, feel free to call me at 612-643-1031.

Defer the tax. Maximize your gain.

© 2022 Copyright Jeffrey R. Peterson All Rights Reserved
1031 Exchange Case Study: Principal Residence Exclusion & Extenuating Circumstances

1031 Exchange

Recently we had a client who was selling their house that they had lived in for less than 2 years. They had about $100,000 in capital gains on the home after expenses. This taxpayer wanted to consider a 1031 exchange and was wondering if it was possible.

Principal Residence Exclusion

A 1031 exchange may not be an option in this case if the house has been used as the taxpayer's principal residence. For the IRC 1031 to qualify, you need to HOLD the replacement property for business or investment purposes.

It’s your home and generally speaking, you can't do a 1031 exchange on your home. That's usually not a big deal because under IRC section 121 the principal residence exclusion you get to take up to $500,000 of that profit tax return married filing a joint tax return or $250,000 for single filing.

Extenuating Circumstances

But what if you must move early (prior to the two year period) because of:

  • Job related circumstances?

  • Health reasons?

  • Or other unforeseen circumstances?

You may still be able to take a portion of the two year exclusion if any of the following apply.

121(c)(2) EXCLUSION FOR TAXPAYERS FAILING TO MEET CERTAIN REQUIREMENTS:

(2) Sales and exchanges to which subsection applies. This subsection shall apply to any sale or exchange if:

(A) subsection (a) would not (but for this subsection) apply to such sale or exchange by reason of--

(i) a failure to meet the ownership and use requirements of subsection (a), or

(ii) subsection (b)(3), and

(B) such sale or exchange is by reason of a change in place of employment, health, or, to the extent provided in regulations, unforeseen circumstances.

Contact CPEC1031, LLC

Contact us today with any questions you have about your 1031 exchange. Our team of qualified intermediaries is on hand to guide you through the process and make sure your exchange is set up for success. You can reach us at our primary office in downtown Minneapolis.

  • Start Your 1031 Exchange: If you have questions about 1031 exchanges, feel free to call me at 612-643-1031.

Defer the tax. Maximize your gain.

© 2022 Copyright Jeffrey R. Peterson All Rights Reserved
When to Consider a 1031 Exchange of Farmland

1031 Exchange of Farmland

What are the benefits of doing a land exchange on the sale of a ranch or farm? That's our topic for this 1031 exchange educational article. We’ll discuss the different parts of farmland and offer some tips for exchanging farmland in a 1031 transaction.

2 Parts of Farmland

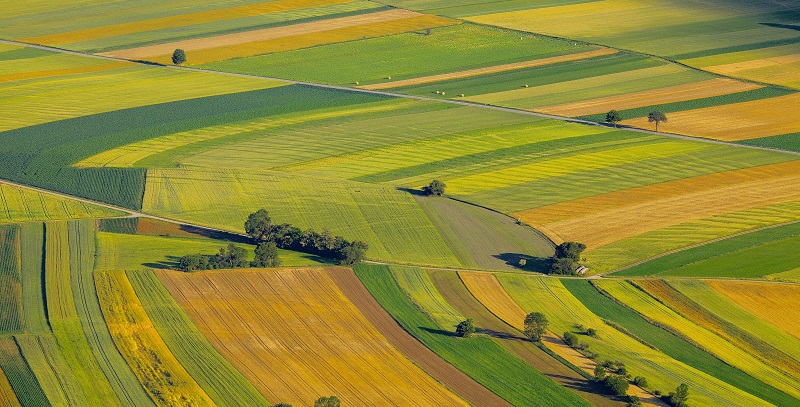
Farmers typically have a large plot of farmland that can be separated into two separate sections for tax purposes:

  1. A small homestead where they live

  2. Lots of tillable acreage on which they grow their crops

Section 121 & Section 1031

These two different parts of the farm can have radically different tax treatment. Under section 121 of the Internal Revenue Code there's a principal residence exclusion for the sale of one's principal residence or domicile that would be applicable to the portion of the property the farmer lives in and the little curtilage around that farmstead. The rest of the acreage is eligible for 1031 tax deferral because it's used in the farm or ranch’s business.

So we can have two different tax treatments for the disposition of one farm or ranch. The best strategy is to try to maximize the tax-saving benefits of both. Selling the family ranch in a 1031 exchange (coupled with a 121 exclusion), can bring huge tax savings for you and your heirs.

Farmland 1031 Exchange Professionals

If you’re considering a 1031 exchange of your farmland, you’ve come to the right place. At CPEC1031, we have been facilitating like-kind exchanges of farms for over twenty years. Our qualified intermediaries can work with you through the entire process and ensure your exchange is a success. Contact us today to learn more about the process and how we can help!

  • Start Your 1031 Exchange: If you have questions about 1031 exchanges, feel free to call me at 612-643-1031.

Defer the tax. Maximize your gain.

© 2022 Copyright Jeffrey R. Peterson All Rights Reserved

Tips for Doing a 1031 Exchange with Auctioned Property

When you go to an auction and sell your 1031 relinquished property it can be challenging because the treasury regulations say that you have to give written notice to the other parties to your sale contract.

No Direct Contact with the Buyer

In an auction sometimes you don't have that direct interconnection with the buyer of your property because it happens so fast and it happens through an auctioneer.

You don't have direct contact with the buyer, but the treasury regulations say that you need to give written notice to the other party to a contract. So oftentimes we suggest that when you put the property up for sale at the auction that you specify that it is part of a 1031 exchange and that your interest in it will be a assigned to the qualified intermediary. That also can be contained in any brochures or flyers that are used to advertise the auction properties.

Tips for Auctioning 1031 Exchange Property

If you really want to be safe and secure the best way to evidence that you gave the proper and requisite notices to the buyer is to find the buyer and ask them to sign a notice that states that you're doing a 1031 exchange, you have assigned your interest in this property and the sale contract to the intermediary.

That's the best way to button up your exchange and verify that you gave written notice, and if you're ever audited now you've got written proof to show that you complied with that requirement. But in a crazy auction environment where deals are happening quickly and property is moving fast it can be challenging, and people do struggle to find a way to give the requisite notice to the other parties.

CPEC1031

Reach out to the qualified intermediaries at CPEC1031 now for help with your next 1031 exchange. We can make sure you have all your bases covered and set you up for a successful like-kind exchange.

  • Start Your 1031 Exchange: If you have questions about 1031 exchanges, feel free to call me at 612-643-1031.

Defer the tax. Maximize your gain.

© 2022 Copyright Jeffrey R. Peterson All Rights Reserved
Have DSTs Replaced TICs for Real Estate Syndication?

Real estate syndications are commonly used by taxpayers conducting 1031 exchanges of real property. In this article, we are going to talk about the current state of real estate syndications and whether DSTs have effectively replaced TICs.

DSTs vs. TICs

To some degree, the old TIC (Tenancy-in-Common) syndications have fallen out of favor. There are still TIC syndicated deals out there and there are instances in which TICs are an easier method for putting together a consortium of buyers.

It’s most popular with friends and family who want to get together and acquire a property as tenants-in-common. I also see it with developers who want to bring in friends and family to buy the “dirt” that will eventually become a development.

However, by and large, DSTs have replaced TICs as the modality for real estate syndication. There is an enormous amount of money going into syndicated real estate right now – particularly DST syndications. There is not enough inventory in the securitized world to satiate the demand. As a result, some firms will have trouble because there will be clients knocking on the door wanting to get in when the deal is already buttoned up.

Contact CPEC1031, LLC

If you have further questions about DSTs or TICs, don’t hesitate to reach out to the team at CPEC1031. Our 1031 exchange intermediaries have over twenty years of experience facilitating exchanges of all shapes and sizes. Contact us today to learn more about how we can help with your 1031 exchange!

  • Start Your 1031 Exchange: If you have questions about 1031 exchanges, feel free to call me at 612-643-1031.

Defer the tax. Maximize your gain.

© 2022 Copyright Jeffrey R. Peterson All Rights Reserved